Free merchant statement reviewPowered by PaybotX
Local to the San Fernando Valley · Serving SoCal

Stop guessing what card processing really costs you.

“I’m local to the Valley. I’ll review your statement with you and walk you through your options: lower your costs, share them, or potentially offset them. No pressure. Your decision.” Drew Lutzke, founder

Book a timedrew@lutzkemerchserv.comLocal to the San Fernando Valley — serving businesses across Southern California.
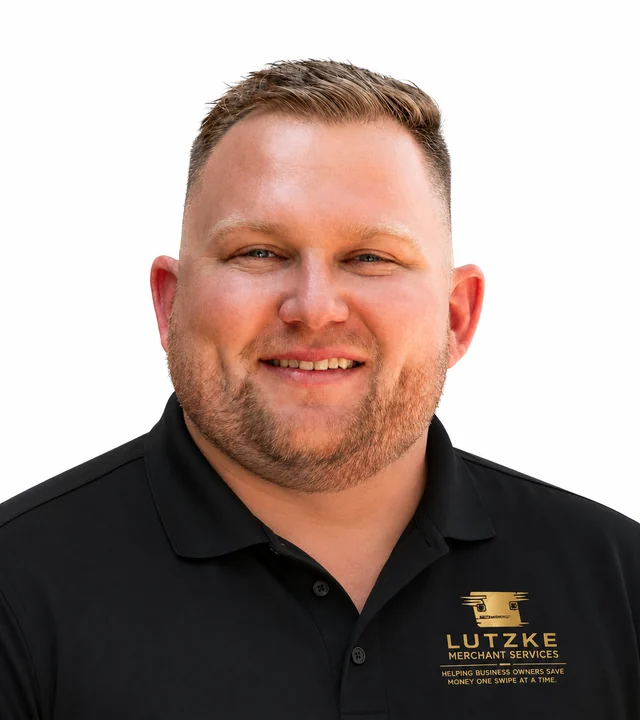
Drew Lutzke, founder of Lutzke Merchant Services, in front of the Los Angeles skyline

Why Lutzke Merchant Services

Statement first

We start with what you actually pay, not a pitch.

Plain language

Every fee named, explained, and put in context.

Three structures

Traditional, Split, and Full Cash Discount, compared side by side.

One direct contact

You book time with Drew directly. A real, local person.

Powered by PaybotX

Modern payment technology behind the scenes. About PaybotX

Who this is for

Established businesses, typically processing $20,000 or more a month in card sales.

Smaller business? You’re still welcome to ask. If a review won’t be worth your time, we’ll tell you.

Know your number

Your statement isn’t just a bill. It’s a diagnostic.

Your costs are spread across interchange, assessments, markup, per-transaction charges, and monthly fees. One number cuts through all of it: your effective rate.

01

Add up every feeRates, per-item charges, monthly and PCI fees, equipment.

02

Find total card volumeGross card sales processed for the same month.

03

Divide fees by volumeThat’s your effective rate, and the starting point for every comparison.

The issue may not be that your processor is doing anything wrong. It may be that no one has shown you another way.

Hypothetical statement for illustration. Real statements vary in layout and fee names.

Lower · Share · Maximize

Pay Less in Processing Fees. Choose How Much Less.

Lower your costs. Share them. Or potentially offset them.

There’s no one-size-fits-all approach to payment processing. We compare your options using your actual numbers — and if your goal is maximum savings, Cash Discount is designed to provide the greatest potential reduction in the processing costs your business absorbs.

Compare My Options
  1. Lower costs
  2. Share costs
  3. Maximize savings
01 · TRADITIONAL

Lower Your Costs

Keep customer pricing unchanged.

You continue absorbing processing costs while we look for opportunities to lower your rates, eliminate unnecessary fees, and reduce your overall processing expense.

Example
Monthly card sales$50,000
Illustrative processing cost at 3%$1,500/mo
Business absorbs
~$1,500/month*
Annual cost
~$18,000/year*
Best for

Businesses that want to keep customer pricing unchanged.

02 · SPLIT CASH DISCOUNT

Share the Cost

Reduce how much your business absorbs.

A portion of the processing cost is accounted for through card pricing while your business absorbs the remainder. Cash customers receive a discount.

Example
Monthly card sales$50,000
Illustrative processing cost at 3%$1,500/mo
Business absorbs
~$750/month*
Card pricing accounts for
~$750/month*
Illustrative annual business cost
~$9,000/year*

Illustrative 50/50 split. The actual split varies by program structure and approved terms.

Best for

Businesses that want meaningful savings with a softer pricing change.

03 · FULL CASH DISCOUNTMaximum savings

Maximize Your Savings

Our maximum-savings option.

Structure your posted card pricing to account for applicable processing costs while offering customers a discount for paying with cash. Depending on your business and approved program terms, this can substantially reduce or potentially offset the processing costs your business currently absorbs.

Example
Monthly card sales$50,000
Illustrative processing cost at 3%$1,500/mo
Potential savings
Up to ~$1,500/month*
Up to ~$18,000/year*
Business absorbs
Potentially ~$0 of the illustrated processing cost*
Best for

Businesses focused on keeping the maximum amount of their revenue.

See My Potential Savings

*Examples are for illustration only and assume $50,000 in monthly card sales and a 3% processing cost. Actual rates, savings, pricing adjustments, program structure, card mix, transaction volume, and eligibility vary. Cash Discount and related programs are subject to applicable laws, card-brand rules, and approved program terms.

How Much Could Your Business Save?

Upload a recent merchant processing statement and we’ll compare your current setup against your available options using your actual numbers.

Get My Free Savings Analysis No obligation. Just a clear look at what you’re paying today and where you may be able to save.

Under a cash discount program, customers who pay by card see a non-cash adjustment (the posted card price), and customers who pay cash receive a discount. Cash discount and surcharge programs are subject to card-brand rules and California law (including Cal. Civ. Code §1748.1 and the state’s Honest Pricing Law). A compliance review is recommended before any program goes live. This isn’t legal advice. Programs are set up only under approved program terms. No savings are guaranteed.

Run the numbers

Same volume. Four different outcomes.

Here’s how the three structures compare on one hypothetical business doing $10,000 a month in card sales.

What the difference can look likeHypothetical example · $10,000/mo card volume
StructureIllustrated merchant costPer monthPer year
Current (hypothetical)3.50% effective rate
$350merchant cost / mo
—difference / yr
TraditionalLower It · hypothetical 2.75%
$275merchant cost / mo
$900difference / yr
Split Cash DiscountShare It · 1.75% / 1.75%
$175merchant cost / mo
$2,100difference / yr
Full Cash DiscountShift It · card pricing covers illustrated 3.50%
Potentially offset*merchant cost / mo
$4,200difference / yr
This is a hypothetical example, not a quote or a typical result. Differences are measured against the hypothetical 3.50% baseline above, not against a “typical” rate. *Under the illustrated Full Cash Discount, the posted card price accounts for the illustrated processing cost; this is not a zero-fee claim. Annual figures = monthly × 12 and assume constant volume, card mix, and pricing. Actual rates, fees, savings, Cash Discount structures, equipment terms, and approval are merchant-specific and subject to underwriting, program rules, card mix, transaction type, and applicable requirements.
See this math with your real numbers.

The table above is hypothetical. Send one recent statement and we’ll show you your actual effective rate and how all three structures compare for your business.

Know your number

Still paying around 3% or more in card fees? Know your number.

Two numbers from your statement. Ten seconds. No email required.

Effective-rate calculator

Do the math on your own statement.

Use one monthly statement. Everything stays in your browser; nothing is sent anywhere. Prefilled values are hypothetical.

$
Gross card sales processed that month.
$
Every processing fee on the statement: rates, per-item, monthly, PCI.
$
Shown separately so you can see your all-in monthly cost.
Your current cost
Effective rate
3.50%
Monthly$875
Quarterly (× 3)$2,625
Annual (× 12)$10,500
Per $100 in card sales$3.50

Effective rate = processing fees ÷ card volume. Not a quote or a benchmark.

Options to compareHypothetical estimates
Split Cash DiscountShare It

The posted card price carries a partial non-cash adjustment, cash customers get a discount, and you absorb the rest of the processing cost.

Illustrated 50/50 split: your shareabout $438/moof today’s processing fees

The actual split is set within approved program terms. Hypothetical estimate.

TraditionalLower It

One price for every customer. Your rate, markup, and monthly fees get reviewed against your statement to look for a lower-cost structure.

Your numberReviewed against your statementNo estimate until we see it

Cash discount and surcharge programs must follow card-brand rules and California law. A compliance review is recommended before any program goes live. Results vary; no savings are guaranteed.
These are hypothetical. See how each option would apply to your actual statement.

Book my free statement review to see your real numbers
How it works

From statement to decision in five clear steps.

See the full process
STEP 01

Discovery call

A short call about how your business takes payments.

STEP 02

Send a statement

One recent monthly statement is enough to start.

STEP 03

Analysis & review

Your effective rate, fees, and all three structures, side by side.

STEP 04

Application & setup

If you move forward: PaybotX application, underwriting, equipment. Approval isn’t guaranteed.

STEP 05

Training & go live

Help getting your team comfortable, plus a local contact after.

A quick hello from Drew13 seconds · captions on screen
Drew Lutzke, founder of Lutzke Merchant Services
Meet DrewDrew LutzkeFounder · Local to the San Fernando Valley

“I’m local. I start with your statement and how your business actually runs. If your current setup is a good fit, I’ll tell you.”

  • Understand before recommending. Your statement and your operation come first.
  • Plain-language explanations. You’ll know what each fee is and why it’s there.
  • Options, not one-size-fits-all. Traditional, Split, and Full Cash Discount, powered by PaybotX.
  • See the structure before you decide. No surprises in the paperwork you sign.
  • Help with the transition. Application, setup, and training if you move forward.
FAQ

Straight answers.

Plain-language answers to what business owners ask most.

All questions
What is an effective rate?

Your total processing fees for the month divided by your total card volume. Hypothetical example: $350 in fees on $10,000 in card volume is a 3.50% effective rate. It’s the single most useful number on your statement.

Who is this for?

Established businesses, typically processing $20,000 or more a month in card sales. Smaller businesses are still welcome to ask.

Is the statement review really free?

Yes. The review is complimentary and there’s no obligation to switch anything. If your current setup is a good fit, we’ll tell you.

Is a cash discount the same as a surcharge?

No. A surcharge is a fee added for paying by credit card. A cash discount program posts the card price and gives customers who pay cash a discount. Both are subject to card-brand rules and California law, so any program must be reviewed and set up under approved terms. This isn’t legal advice.

Do I have to switch processors?

No. The review is information. You decide what, if anything, happens next.

Will I be approved?

Every application is subject to underwriting by the processor and bank. Approval and timing aren’t guaranteed.

What should I not send?

Card numbers, customer data, or any bank or processor login credentials. You can black out your bank account number; we don’t need it for the review.

Free merchant statement review

Know your number. Then decide.

Send one recent statement or book a short call. We’ll review what you’re paying today and whether there’s an opportunity to improve it. No pressure, no obligation.